The short version
The Citi Double Cash is the best free card for most people at 2% back. Food-heavy households earn more with Capital One Savor; travellers need no foreign fee.
The best no annual fee card for most people is the Citi Double Cash, because 2% back on every purchase beats a category card unless a large share of your spending lands in its categories. Food-heavy households do better with the Capital One Savor at 3% on dining and groceries, travellers should carry the Wells Fargo Autograph or Chase Freedom Flex because neither charges a foreign transaction fee,. All six picks cost nothing to hold, and every figure was read on the issuer’s own page on 27 September 2026.
- Start with a flat 2% card. It is the bar every category card has to beat on your actual statement.
- Check the foreign fee before you travel. The Double Cash and Freedom Unlimited charge 3%; the Savor, Autograph, Freedom Flex and Bank of America Travel Rewards charge none.
- Free cards still have bonuses: $200 to $250 in cash, or 20,000 points, for spending of $500 to $1,500.
- Skip rewards entirely if you carry a balance. These cards charge up to 28.74% after any intro period.
The six picks at a glance
Each card wins a different job: flat cash, food, travel spending, rotating bonuses, a 0% runway, or simplicity abroad.
| Card | How it earns | Welcome bonus | Intro APR | Foreign fee |
|---|---|---|---|---|
| Citi Double Cash | 2% on everything (1% buy, 1% pay) | $200 after $1,500 in 6 months | 0% on balance transfers, 18 months | 3% |
| Capital One Savor | 3% dining, entertainment, streaming, grocery stores; 1% other | $200 after $500 in 3 months | 0% purchases and transfers, 12 months | None |
| Wells Fargo Autograph | 3X restaurants, travel, gas and transit, streaming, phone plans; 1X other | 20,000 points after $1,000 in 3 months | 0% purchases, 12 months | None |
| Chase Freedom Flex | 5% on up to $1,500 a quarter in rotating categories; 3% dining and drugstores; 1% other | $250 after $500 in 3 months | 0% purchases and transfers, 15 months | None |
| Chase Freedom Unlimited | 3% dining and drugstores; 1.5% other | $200 after $500 in 3 months | 0% purchases and transfers, 15 months | 3% |
| Bank of America Travel Rewards | 1.5 points per $1 on everything | Check the issuer | 0% purchases, and transfers made in 60 days, 15 billing cycles | None |
Best flat-rate card, Citi Double Cash
The Double Cash pays 2% on every purchase with no caps or categories, and that simplicity is why it earns the most for a typical spender. The catch is in how the 2% arrives: 1% when you buy and 1% as you pay the bill, so it rewards people who clear their balance. Its intro offer is 0% on balance transfers for 18 months (a 3% fee in the first four months, then 5%), with nothing on purchases.
Who should pick something else: anyone who travels abroad, because Citi charges 3% on foreign purchases, which is more than the card pays back. The Wells Fargo Active Cash is the alternative flat card, at unlimited 2% with 0% on purchases for 12 months, but it also charges 3% abroad.
Best for groceries and dining, Capital One Savor
The Savor pays an uncapped 3% at grocery stores and restaurants, on entertainment and on popular streaming, which makes it the strongest free card for a household that spends most of its budget on food. Capital One excludes superstores such as Walmart and Target from its grocery category, so a family that shops there should count those purchases at 1%. There is no foreign transaction fee, and after the 12-month intro period the APR is 18.49% to 28.49% variable.
If your supermarket spend is modest and capped spending suits you, the American Express Blue Cash Everyday is the other free food card, at 3% on up to $6,000 a year at US supermarkets. It charges a 2.7% foreign fee, so it stays at home.
Best for travellers, Wells Fargo Autograph and Chase Freedom Flex
Both cards earn well on the road and neither charges a foreign transaction fee, which is the first test a travel card has to pass. The Autograph pays 3X on restaurants, travel, gas and transit, popular streaming and phone plans, and Wells Fargo lists cell phone protection up to $600 with a $25 deductible.
The Freedom Flex dropped its foreign fee on 21 September 2026, which changes where it belongs in a wallet. It pays 5% on up to $1,500 in combined purchases each quarter you activate; for October to December 2026 the categories are grocery stores (excluding Walmart and Target), dining and American Red Cross donations. It also lists trip cancellation cover of up to $1,500 per traveller and $6,000 per trip. Card cover of that size is not trekking insurance; read the gap in card travel insurance that a trek walks into before relying on any card for a mountain trip.
Best 0% runway, Chase Freedom Unlimited
The Freedom Unlimited gives 0% on purchases and balance transfers for 15 months, plus 3% on dining and drugstores. Everything else earns 1.5%, it charges a 3% foreign fee, and it only out-earns the Double Cash when dining and drugstores are more than half of your other spending.
Simplest card to carry abroad, Bank of America Travel Rewards
The Travel Rewards card earns 1.5 points per dollar on everything and charges no foreign transaction fee, which makes it a dependable one-card answer for a trip. After its intro period the APR is 17.49% to 27.49% variable. We could not confirm its current welcome bonus on the issuer’s page, so check it before applying.
What each card earns on a real budget
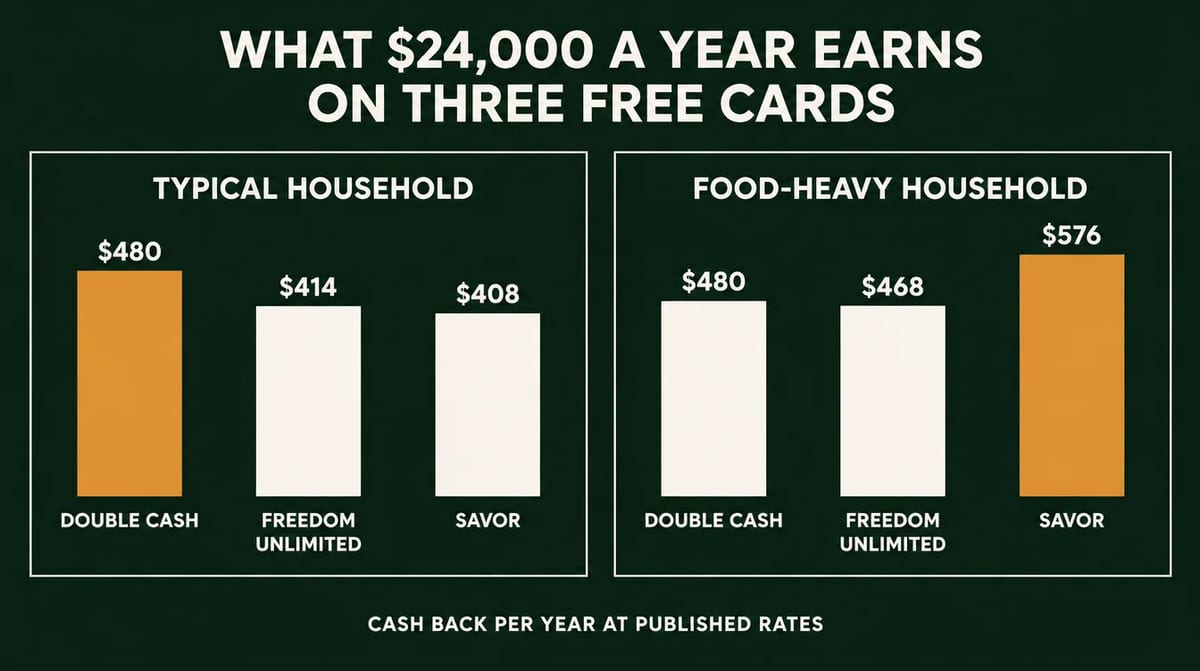
A flat 2% card wins for a typical budget, and a food card overtakes it only when groceries and dining are most of the bill. Here are two households each spending $24,000 a year, run through the three cash-back picks at their published rates, assuming the groceries are bought at supermarkets rather than superstores.
| Yearly spend | Double Cash | Freedom Unlimited | Savor |
|---|---|---|---|
| Household A: $4,800 groceries, $3,600 dining, $2,400 gas, $13,200 other | |||
| Cash back | $480 | $414 | $408 |
| Household B: $9,600 groceries, $7,200 dining, $2,400 gas, $4,800 other | |||
| Cash back | $480 | $468 | $576 |
Household A shows the power of the flat rate: the Savor earns 3% on $8,400 of food ($252) but only 1% on the other $15,600 ($156). Household B spends $16,800 on food, and the Savor’s $504 on groceries and dining plus $72 on the rest pulls clear. The Freedom Unlimited sits between them in both cases. We left the Autograph out because it pays points, and we do not assign a value to points.
On a $3,000 trip, a 3% foreign fee costs $90, more than the $60 a 2% card earns. Carry one of the no-fee cards above, pay in the local currency rather than dollars, and read how to avoid foreign transaction and ATM fees before you go.
The verdict
Get the Citi Double Cash as your default card, add the Capital One Savor if food is most of your spending, and carry the Autograph or Freedom Flex when you travel. If you want one card for home and abroad, the Savor is the best all-rounder here. When a paid card starts to make sense instead, our guide to whether a travel card’s annual fee is worth it shows the arithmetic.
And if you carry a balance from month to month, ignore rewards altogether. Every card here charges between 17.49% and 28.74% once its intro period ends, and a single month of interest on a modest balance can cancel a year of cash back.
Nepal is where a modest travel fund goes furthest. Annapurna Base Camp is nine days at $920 USD solo and Everest Base Camp is twelve days at $1,700 USD solo, including permits, a government-registered guide, a porter, teahouses and meals.
See the Annapurna Base Camp trek →What is the best no annual fee credit card in 2026?
For most people, the Citi Double Cash, at 2% on every purchase. Households that spend mostly on groceries and dining earn more with the Capital One Savor, and travellers should pick a card with no foreign transaction fee, such as the Savor, the Wells Fargo Autograph or the Chase Freedom Flex.
Which no annual fee cards have no foreign transaction fee?
Of the cards in this guide, the Capital One Savor, Wells Fargo Autograph, Chase Freedom Flex (from 21 September 2026) and Bank of America Travel Rewards charge no foreign transaction fee. The Citi Double Cash, Chase Freedom Unlimited and Wells Fargo Active Cash charge 3%.
Is a flat-rate card better than a category card?
Usually, unless a large share of your spending falls in the category card’s bonus categories. Against a flat 2% card, a card paying 3% on categories and 1.5% elsewhere only wins when category spending is more than half of everything else.
Which free card has the longest 0% period?
For purchases, the Chase Freedom Unlimited and Freedom Flex offer 15 months, and Bank of America Travel Rewards offers 15 billing cycles. For balance transfers, the Citi Double Cash offers 18 months, with a transfer fee.
Do no annual fee cards have welcome bonuses?
Yes. As of 27 September 2026 the bonuses in this guide range from $200 to $250 in cash, or 20,000 points on the Wells Fargo Autograph, for spending between $500 and $1,500 in the first three to six months.
Keep reading
The four decisions that choose a card, with every comparison in one place.
When a paid card beats a free one.
The card-machine question that costs travellers most.
The costly habits most travellers repeat.
How earning and redeeming really work.
Sources: Citi, Double Cash card page and pricing details; Capital One, Savor card page; Wells Fargo, Autograph and Active Cash card pages; Chase, Freedom Flex and Freedom Unlimited card pages, pricing and terms, and the 21 September 2026 Freedom Flex announcement; American Express, Blue Cash Everyday card page and rates and fees; Bank of America, Travel Rewards card page. All read on 27 September 2026. The household examples are our own arithmetic on those published rates. This is general information, not financial advice; card offers change, so confirm the current terms with the issuer before you apply. No card issuer pays us for placement on this page.
Written by
Bishnu AdhikariPokhara-based, NMA-certified trekking guides. We’ve led 5,000+ treks across the Annapurna and Everest regions since 1998 — every word here comes from the trail. More from this author →
Share this article
Ready to Trek?
From reading about it to standing on it
Our Pokhara-based guides have been doing this since 1998. Tell us your dates and fitness level — we'll build your perfect itinerary. Free, no obligation.
Why trek with our licensed agencyMore guides like this
Popular trips to consider
View all treks & toursFree Trekker’s Insider Guide
Permits, packing lists, cost breakdowns — no fluff.
We send one useful email. You can unsubscribe anytime.