The short version
Lloyds Ultra is the best card to take abroad for most people: no foreign fee and 1% cashback in year one. Barclaycard Rewards is the other no-fee pick.
For most UK travellers the Lloyds Ultra is the best card to take abroad: no foreign transaction fee, 1% cashback in the first year and the lowest representative rate here, at 14.9% APR variable. The Barclaycard Rewards is the other no-fee option, with fee-free cash withdrawals abroad too. If you collect Avios, the free Barclaycard Avios earns one per pound but charges on foreign spending. And the American Express Preferred Rewards Gold buys you four lounge visits a year for £195 after a free first year. Every figure below was read on the issuer’s own site on 27 September 2026.
- Lloyds Ultra for most people: no foreign transaction fee, no monthly fee, 1% cashback in year one then 0.25%.
- Barclaycard Rewards if you want no fees abroad, including a 0.00% fee on cash withdrawals, and 0.25% cashback.
- Barclaycard Avios if Avios are the goal and you mainly spend at home: free, but 2.99% on non-sterling purchases.
- Amex Preferred Rewards Gold if lounges matter: four Priority Pass visits a year, but a 2.99% non-sterling fee and a representative 85.8% APR variable once the fee is counted.
- Pick none if you carry a balance — interest will cost more than any cashback or points.
The four cards side by side
Two of the four charge nothing on foreign spending, and those two are the ones to take abroad. The table uses each issuer’s own representative example. Your rate depends on your circumstances and may differ.
| Lloyds Ultra | Barclaycard Rewards | Barclaycard Avios | Amex Preferred Rewards Gold | |
|---|---|---|---|---|
| Account fee | None | Not stated on the card page | £0 a month | £195 a year (£0 first year) |
| Non-sterling purchase fee | None | None | 2.99% (Barclaycard standard) | 2.99% |
| Earns | 1% cashback year one, then 0.25% | 0.25% cashback | 1 Avios per £1 | 1 point per £1; 2 on airlines direct; 3 on Amex Travel |
| Welcome offer | — | — | 5,000 Avios after £1,000 in 3 months | 20,000 points after £3,000 in 3 months |
| Representative example | 14.9% APR variable; purchase rate 14.94% a year variable; £1,200 | 28.9% APR variable; purchase rate 28.9% p.a. variable; £1,200 | 29.9% APR variable; purchase rate 29.9% p.a. variable; £1,200 | 85.8% APR variable; purchase rate 29.1% p.a. variable; £1,200 |
Why the non-sterling fee decides it
A 2.99% non-sterling fee costs £29.90 on every £1,000 you spend abroad, which is more than most cards earn back in rewards. Barclaycard’s own help pages list a 2.99% non-sterling purchase fee and a 2.99% cash fee (£2.99 minimum) on its cards that do not waive them, and American Express lists 2.99% in the Gold card’s summary box.
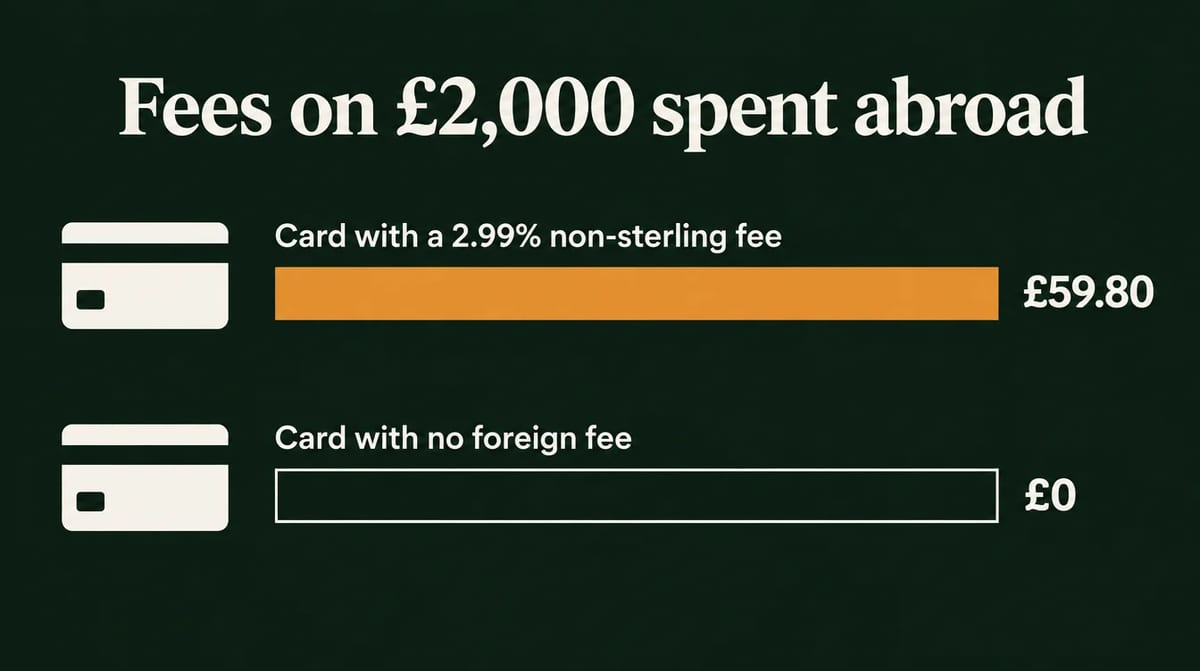
| £2,000 spent abroad | Foreign fee | Rewards earned |
|---|---|---|
| Lloyds Ultra (year one) | £0 | £20 cashback |
| Barclaycard Rewards | £0 | £5 cashback |
| Barclaycard Avios | £59.80 | 2,000 Avios |
| Amex Preferred Rewards Gold | £59.80 | 2,000 points |
Whether 2,000 Avios or points are worth more than £59.80 depends entirely on how you redeem them, and we will not pretend to know that for you. The simpler rule: use a no-fee card for anything priced in a foreign currency, and keep reward cards for spending at home. Whatever card you use, pay in the local currency when a terminal abroad offers pounds — our guide to dynamic currency conversion explains why.
Lloyds Ultra, the best all-rounder abroad
The Ultra combines no foreign transaction fee with cashback and a low rate, which is a rare mix. Lloyds pays 1% cashback on all card purchases in the first year from account opening and 0.25% after that. There is no monthly account fee, and Lloyds charges no fee of its own on cash withdrawals, though interest applies and ATM operators may add a charge. The representative example is 14.9% APR variable, based on borrowing £1,200 at a purchase rate of 14.94% a year variable.
Who should pick something else: anyone who wants points for flights rather than cashback, and anyone Lloyds declines — the eligibility checker shows your likely rate and limit without affecting your credit score.
Barclaycard Rewards, no fees abroad including cash
Barclaycard Rewards charges nothing abroad on purchases and shows a 0.00% fee on all cash withdrawals, with 0.25% cashback on everyday spending. Representative 28.9% APR variable, purchase rate 28.9% p.a. variable, based on a £1,200 limit. The cashback is credited once a year or on request.
The trade-off against the Ultra is the rate: roughly double if you ever carry a balance. As a card you clear in full each month and use only abroad, it does the job well. Remember that taking cash on any credit card usually starts interest immediately, so for ATM cash a debit card or travel money account is often cheaper. Our guide to avoiding foreign transaction and ATM fees covers the options.
Barclaycard Avios, the free way to collect Avios
The Barclaycard Avios earns 1 Avios per pound with no monthly fee, and 5,000 bonus Avios if you are new to Barclaycard and spend £1,000 in three months. Spend £20,000 in 12 months and you can choose a British Airways cabin upgrade voucher or 7,000 bonus Avios. Representative 29.9% APR variable, purchase rate 29.9% p.a. variable, based on £1,200.
Its sibling, the Barclaycard Avios Plus, earns 1.5 Avios per pound and offers 25,000 Avios after £3,000 in three months, but costs £20 a month, which is why its representative APR is 80.1% variable. Neither card page advertises a waiver of the non-sterling fee, so leave these at home when you travel. For how Avios and other points actually get spent, read miles and points for beginners.
Amex Preferred Rewards Gold, for lounge access
The Gold’s real draw is four complimentary Priority Pass lounge visits a year and a free first year; after that it costs £195. It earns 1 Membership Rewards point per pound, 2 on purchases made directly with airlines and 3 on American Express Travel, and the current new-cardmember offer is 20,000 points after £3,000 in the first three months. Points can transfer to partners such as British Airways Executive Club. You need an income of at least £20,000, and you are not eligible for the bonus if you have held a personal Amex in the past 24 months.
The representative example is 85.8% APR variable at a purchase rate of 29.1% p.a. variable on an assumed £1,200 limit — the APR is high because it includes the £195 fee. Add the 2.99% non-sterling fee and this is a card to use for booking travel at home, not for spending on the trip itself. Our lounge access guide compares it with paying for passes.
Card travel cover is written for ordinary trips. If you are trekking above 3,000 metres, read the gap in card travel insurance that a trek walks into before relying on it.
Taking a UK card to Nepal
In Nepal even the best no-fee card is a city tool: cards work at a small number of upmarket hotels, large agencies and perhaps one or two restaurants per city, usually with a 3–4% surcharge, and not at all on the trail. That is our own field reporting. Nepali ATMs charge about NPR 500 per withdrawal on top of anything your bank adds, so take out large amounts in Kathmandu or Pokhara, carry two cards on two networks, and plan to pay teahouses in rupees.
If the points are for a big trip, Nepal is where a modest balance goes furthest. Annapurna Base Camp is nine days at $920 USD solo and Everest Base Camp is twelve days at $1,700 USD solo, including permits, a government-registered guide, a porter, teahouses and meals.
See the Annapurna Base Camp trek →What is the best credit card to use abroad in the UK?
For most people the Lloyds Ultra, which charges no foreign transaction fee and pays 1% cashback in its first year, with a representative 14.9% APR variable. The Barclaycard Rewards is the other no-fee option, at a representative 28.9% APR variable.
Which UK credit cards have no foreign transaction fees?
Of the cards we checked, the Lloyds Ultra and the Barclaycard Rewards. Barclaycard’s Avios cards and the Amex Preferred Rewards Gold charge 2.99% on non-sterling purchases.
Is the Amex Preferred Rewards Gold worth £195?
Only if you use the four lounge visits and redeem the points well. The first year is free, so it can be worth trying for a year and cancelling before the fee if it does not earn its keep.
Can I withdraw cash abroad on a UK credit card?
Yes, but interest usually starts on the day of the withdrawal, and many cards add a cash fee. Barclaycard Rewards shows a 0.00% fee on cash withdrawals and Lloyds Ultra charges no fee of its own, but interest still applies, so a debit card is often cheaper for ATM cash.
Should I get a rewards card if I carry a balance?
No. At purchase rates of roughly 15% to 30%, interest on a carried balance outweighs cashback or points. Pay in full each month, or choose a card built for low interest.
Keep reading
The four decisions that choose a card, with every comparison in one place.
The card-machine question that costs travellers most.
The four charges on a trip abroad, and how to dodge them.
Where points genuinely beat paying cash.
What card travel cover actually pays for.
Sources: Lloyds Bank, Ultra credit card page; Barclaycard, Rewards card page, Avios card page, rewards cards comparison page and help page on using your card abroad; American Express UK, Preferred Rewards Gold card page and summary box (February 2026 edition). All read on 27 September 2026; representative examples are quoted as each issuer states them. Card use in Nepal is Travel Himalaya Nepal field reporting. The fee table is our own arithmetic. This is general information, not financial advice; card offers change, so confirm the current terms with the issuer before you apply. No card issuer pays us for placement on this page.
Written by
Bishnu AdhikariPokhara-based, NMA-certified trekking guides. We’ve led 5,000+ treks across the Annapurna and Everest regions since 1998 — every word here comes from the trail. More from this author →
Share this article
Ready to Trek?
From reading about it to standing on it
Our Pokhara-based guides have been doing this since 1998. Tell us your dates and fitness level — we'll build your perfect itinerary. Free, no obligation.
Why trek with our licensed agencyMore guides like this
Popular trips to consider
View all treks & toursFree Trekker’s Insider Guide
Permits, packing lists, cost breakdowns — no fluff.
We send one useful email. You can unsubscribe anytime.